Best Credit Cards with No Foreign Transaction Fees in 2026
For zero foreign transaction fees at the lowest annual fee in 2026, the best picks are the Bilt Blue ($0 AF, transferable airline miles, no FTF) and Capital One Venture ($95 AF, 16 airline partners, no FTF). At the premium tier every major travel card waives FTFs by default — but most cashback cards still charge 3%, which is $150 on $5,000 of international spend.
On this page▾
Topic Collection
Part of the Keep or Cancel Collection
Explore all 38 articles
Quick answer
For zero foreign transaction fees in 2026 at the lowest AF, your best options are Bilt Blue ($0 AF, transferable airline miles, no FTF), Autograph ($0 AF, 3x travel + no FTF), and Venture ($95 AF, 16 airline partners, no FTF). At the premium tier, every major travel card waives FTFs by default.
Three structural facts about FTFs in 2026:
- Most travel-positioned cards have eliminated FTFs. Sapphire Preferred/Reserve, Venture/Venture X, Amex Gold/Platinum, Citi Strata Premier all waive the standard 3% fee.
- Most cashback cards still charge 3% FTF. Citi Double Cash, Citi Custom Cash, Capital One Quicksilver, Wells Fargo Active Cash, Discover It Cash Back — all charge. Verify before international use.
- The 3% adds up fast. $5,000 of international spend with a 3% FTF = $150 in unnecessary fees. Two weeks of European meals + hotels easily hits that threshold.
TL;DR: The best credit cards with no foreign transaction fees in 2026 include all major travel-positioned cards (Sapphire Preferred, Sapphire Reserve, Venture, Venture X, Amex Gold, Amex Platinum, Bilt Blue, Citi Strata Premier). The $0-AF Bilt Blue is uniquely powerful because it ALSO offers 1:1 transfer partners to Aeroplan, Alaska Mileage Plan, Hyatt, and Hilton (Bilt's separate AAdvantage transfer partnership wound down in June 2024).
Top picks at a glance
| Card | Annual fee | Best for |
|---|---|---|
| Bilt Blue | $0 | Only $0-AF with no FTF + transferable airline miles |
| Autograph | $0 | $0-AF with 3x travel + restaurants + no FTF |
| Venture | $95 | Low-AF with 16 airline transfer partners + no FTF |
| Sapphire Preferred | $95 | 14 transfer partners + premium travel insurance + no FTF |
| Amex Gold | Mid-AF | 18+ airline transfer partners (incl. ANA) + 4x dining + no FTF |
1. Bilt Blue — only $0-AF with transferable airline miles + no FTF
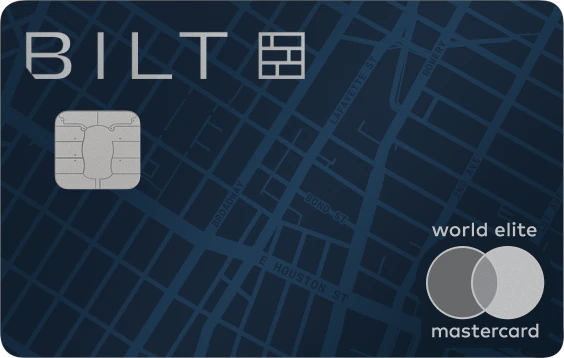
Earns Bilt Rewards on rent payments without transaction fees. Transfers 1:1 to Aeroplan, Alaska Mileage Plan, United, Hawaiian, Cathay Asia Miles, World of Hyatt, and Hilton Honors (Bilt's separate AAdvantage transfer partnership wound down in June 2024). No foreign transaction fees. The only card on the market combining all three: $0 AF, FTF-free, and transferable airline miles at 1:1.
2. Autograph — best $0-AF travel earner with no FTF
3x on travel, restaurants, gas, transit, popular streaming, AND phone plans. No FTF. No transfer partners (cashback-equivalent only) but the high 3x rate on travel-adjacent spend makes this an excellent $0-AF catch-all for international travellers who don't need transferable currency.
3. Venture — best low-AF with transferable miles + no FTF
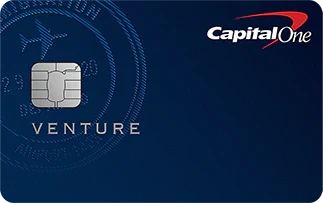
$95 AF, 2x on every purchase, no FTF. Transfers 1:1 to 16 airline partners including Aeroplan, Singapore KrisFlyer, Virgin Atlantic, Cathay Asia Miles, Air France Flying Blue, and British Airways Avios. Best for travellers wanting transferable-currency flexibility at low AF without paying premium-tier benefits they don't use.
4. Sapphire Preferred — premium travel insurance + no FTF
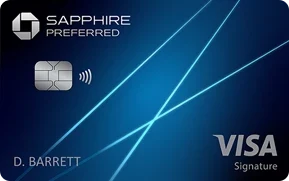
$95 AF, 14 transfer partners, no FTF. Plus the best $95-AF travel insurance in the industry: primary auto rental coverage in most countries, trip-cancellation/interruption ($10,000+ per trip), baggage delay ($100/day for 5 days). For international travellers needing insurance protection, this card alone often justifies the AF.
5. Amex Gold — best Amex MR earner with no FTF
4x dining + 4x US groceries + 3x flights direct + no FTF. Transfers to 18+ airlines including ANA Mileage Club (the only 1:1 ANA access at this AF tier), Delta SkyMiles, Singapore KrisFlyer, Virgin Atlantic, and Aeroplan. The best card for travellers wanting maximum dining points + international transfer-partner reach.
Decision framework: which card wins at your spend level
- Spend <$2,000/year internationally, $0 AF is non-negotiable: Bilt Blue. It is the one $0-annual-fee card here with no foreign transaction fee AND 1:1 transfers to Hyatt and Aeroplan. Be clear about what you are buying: the card itself earns 1x, so the case is the transfer access, not the multiplier.
- Spend $2,000–$6,000/year internationally, want transferable miles: Bilt Blue ($0 AF). At $0.015/pt, even 20,000 Bilt points transferred to Hyatt = $300+ in hotel value — and you paid $0 AF to get there.
- Spend $6,000+/year internationally, want transfer partners + insurance: Chase Sapphire Preferred ($95 AF). The $95 pays for itself before you even use the transfer partners: the primary auto rental coverage alone replaces $30/day collision damage waiver at the rental counter.
- Spend $8,000+/year on dining + want premium transfer reach: Amex Gold. 4x dining at $0.015/pt = $0.06 back per dollar, versus 2x on Venture ($0.03/pt) — Gold wins by $300/year at $8,000 dining spend.
Real use case: two-week Europe trip on $4,000 budget
Scenario: $4,000 in international spend — $1,500 dining, $1,500 hotels, $700 ground transit, $300 miscellaneous.
| Card | Earn rate | Points earned | Value at $0.015/pt | FTF saved vs. 3% card |
|---|---|---|---|---|
| Capital One Venture | 2x everything | 8,000 miles | $120 | $120 |
| Chase Sapphire Preferred | 3x dining, 2x hotels/transit, 1x misc | 9,500 UR pts | $143 (at $0.015/pt) | $120 |
Bottom line: On a $4,000 Europe trip, using CSP instead of a 3% FTF card saves $120 in fees AND earns $143 in transferable points — a $263 swing over a typical cashback card with FTF.
Common mistakes
1. Using a cashback card abroad. Quicksilver, Active Cash, Custom Cash all charge 3% FTF — silently. Always check your card's fee schedule before international purchases.
2. Mistaking FTF-free for currency-conversion-fee-free. FTF and dynamic currency conversion (DCC) are different. DCC is offered at point-of-sale ("would you like to pay in USD?"). Always say NO — DCC costs 3-7% extra. Pay in the local currency and let your card handle conversion at the Mastercard/Visa/Amex network rate.
3. Cancelling a no-FTF card before a known international trip. Cards typically take 7-10 days to ship. Don't be stuck without a working card abroad.
Related content
- Currency hubs: Chase Ultimate Rewards program guide · Amex Membership Rewards program guide · Capital One Miles program guide
- International travel: Best credit cards for international travel
- Cornerstone hubs: Aeroplan guide · Flying Blue guide · Hilton Honors guide
More from the network
- Visa-only purchases (Costco): Best credit cards for Costco
Compare deeper
- Side-by-side comparison: American Express Gold Card vs Chase Sapphire Preferred
- Side-by-side comparison: American Express Gold Card vs Capital One Venture Rewards Credit Card
- Side-by-side comparison: Capital One Venture Rewards Credit Card vs Chase Sapphire Preferred
More compare matchups
- Compare head-to-head: American Express Gold Card vs Chase Sapphire Preferred
- Compare head-to-head: American Express Gold Card vs Capital One Venture Rewards Credit Card
- Compare head-to-head: Capital One Venture Rewards Credit Card vs Chase Sapphire Preferred
Get weekly card offer alerts
Sunday digest of elevated bonuses. One email, zero spam.
Cards mentioned in this guide
Frequently asked questions
Which $0-AF credit card has no foreign transaction fees?
Do FTF-free cards work everywhere internationally?
What is the difference between FTF and dynamic currency conversion?
Related guides
Card Roundups
Best Credit Cards for Airline Miles in 2026
7 min
Card Roundups
Best Credit Cards for Commuters and City Transit 2026
10 min
Card Roundups
Best Credit Cards for Weekend Getaways in 2026
4 min
Strategy
Venture X vs Chase Sapphire Reserve vs Amex Platinum: Which Premium Card Earns Its Fee in 2026?
13 min
Related news
bilt · Jun 2, 2026
Bilt Palladium vs CSR vs Amex Platinum 2026 ($495/$795/$895)
airlines · Jun 2, 2026
Aeroplan 2026: SQC Status and June 1 Devaluation
chase · Jun 10, 2026
Chase Hyatt Transfer Ratio 4:3: What It Means for Sapphire Preferred and Ink Business Preferred
chase · Jun 10, 2026
Chase to Virgin Atlantic: 30% Transfer Bonus — Book Delta Business Class for 18,000 Points
Cards in this ecosystem
Considering switching?