Best Credit Cards for Commuters and City Transit 2026
Amex Green (3x, uncapped) and Wells Fargo Autograph Journey (3x, $95 AF) pay the highest real transit rates; Chase Sapphire Preferred covers the same broad category at 2x. Chase Sapphire Reserve dropped transit to 1x in its 2025 refresh, though its $300 credit still auto-covers real-world transit spend, unlike Capital One Venture X's $300 credit, which only applies inside its own travel portal. None of the major bank point currencies transfer to Amtrak Guest Rewards — only Bilt Rewards does, at 1:1.
On this page▾
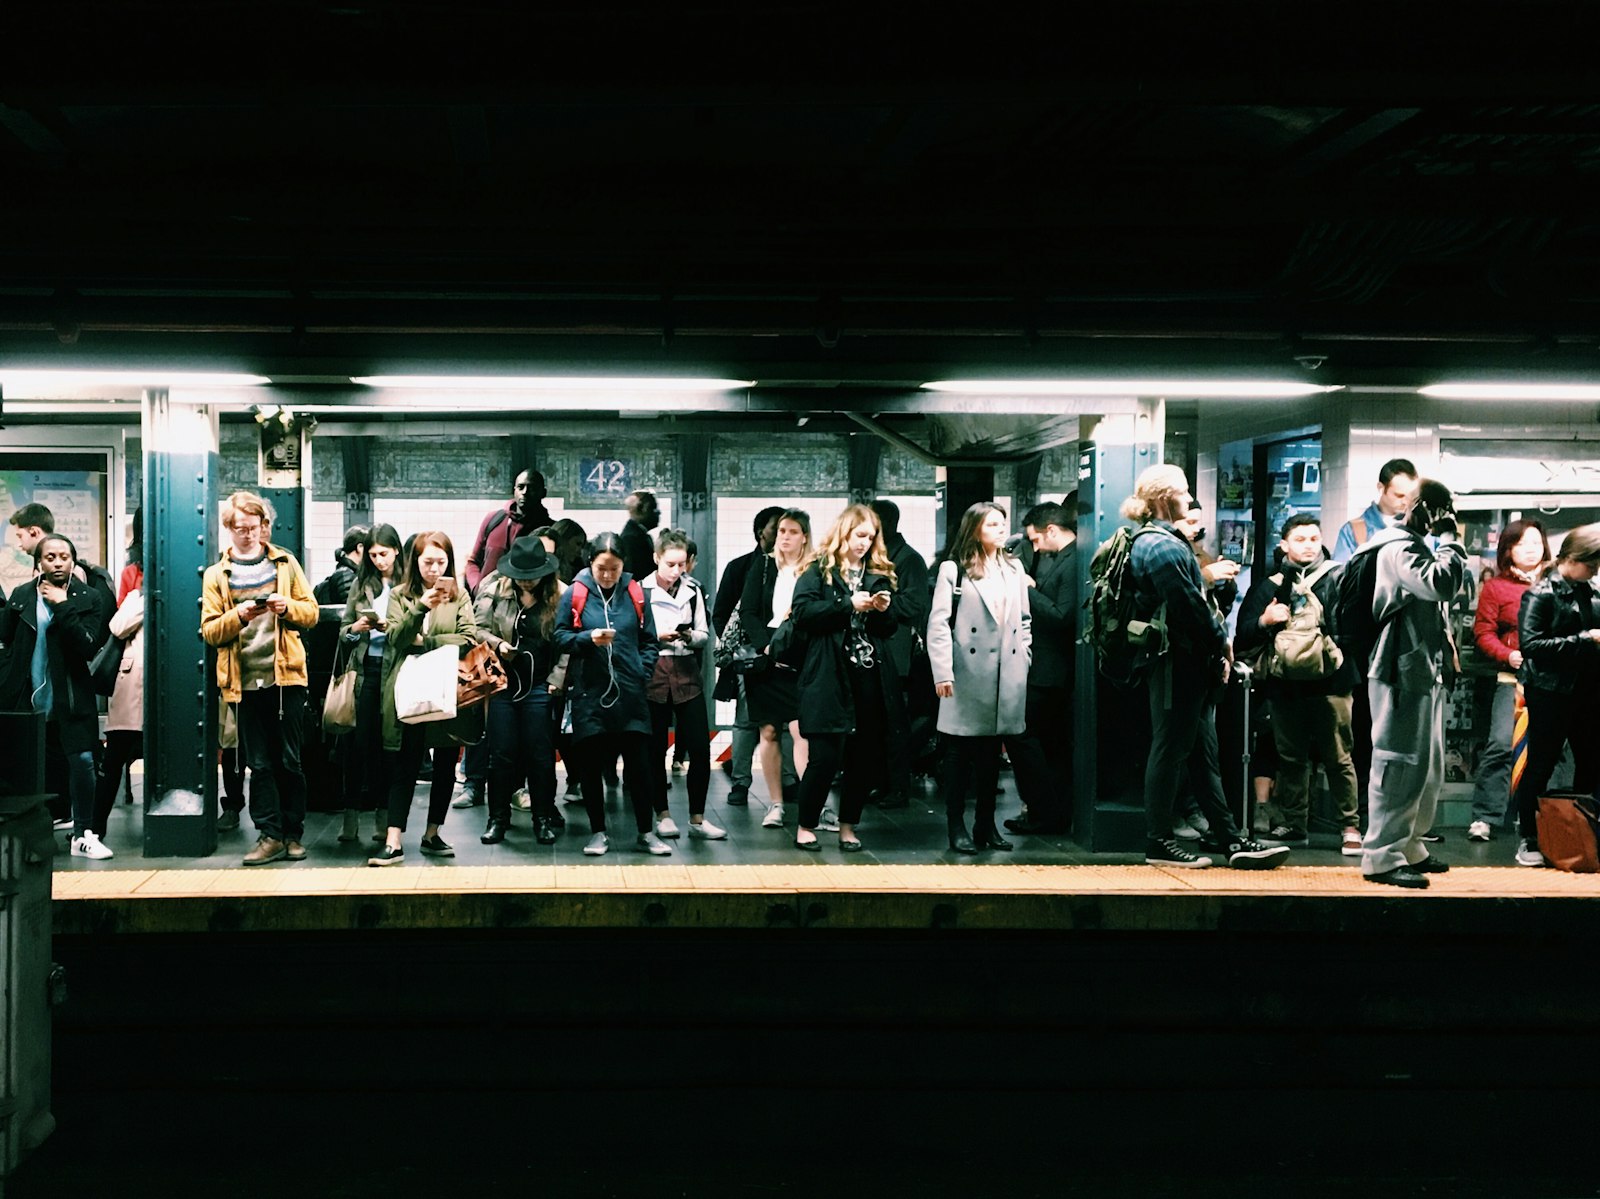
Transit is one of the most under-used bonus categories in the entire rewards system. Most cardholders route their commute spend to whatever card is on top of the wallet, when a handful of cards pay 2-3x on tolls, parking, subway fares, and rideshare — categories most "best travel card" articles skip because they don't sound glamorous.
The catch: multipliers on transit vary more than almost any other category, a few premium cards quietly dropped their transit rate in 2025-2026 refreshes, and the credits marketed as "travel credits" don't all cover transit the same way. This guide sorts out what actually counts, which cards pay for their annual fee on transit spend alone, and where Amtrak fits into the math. All rates verified against issuer terms and MCC documentation in August 2026.
Quick answer
For a straightforward commute — subway, bus, tolls, parking, rideshare — Amex Green and Autograph Journey both pay a real 3x, and Sapphire Preferred's broad 2x travel category covers the same spend at a lower annual fee. Sapphire Reserve dropped its transit multiplier to 1x in its 2025 refresh — its $300 credit still reimburses transit dollar-for-dollar up to the cap, but the ongoing rate no longer rewards commuting. Venture X's $300 credit only applies inside its own travel portal, so it does nothing for a toll booth or a subway turnstile.
- Best flat transit multiplier: Amex Green — 3x on trains, buses, subways, tolls, parking, and rideshare, no cap.
- Best transit multiplier at a lower AF: Autograph Journey — 3x ground transportation, $95 AF.
- Best broad-travel card that still covers transit: Sapphire Preferred — 2x, $95 AF.
- Best if transit is a small slice of bigger travel spend: Sapphire Reserve — $300 credit clears fast on transit, but only 1x ongoing.
- Best for building outsized Amtrak value: transferring points to Amtrak Guest Rewards, where a Bilt card is the only real transfer path.
Key takeaway: three cards actually reward transit at an elevated rate; two premium cards market travel credits that only partly — or barely — help a commuter.
What actually counts as "transit," and where rideshare splits off
Card networks group transit purchases by merchant category code (MCC), and the group is broader than most people expect: subway and bus fares, commuter rail, ferries, tolls, parking lots and garages, taxis, and rideshare apps (Uber, Lyft) typically all code under the same transportation umbrella that issuers use for elevated transit rates. Bike-share systems (Citi Bike, Bluebikes) don't have one standardized code and can post as either transportation or recreation depending on the operator — check your statement rather than assume.
Rideshare's split happens somewhere else entirely: the federal pre-tax commuter benefit under IRS Section 132(f) — up to $340/month tax-free in 2026 for transit passes, vanpooling, and parking — explicitly excludes standard Uber and Lyft rides, since they don't meet the "mass transit" or "commuter highway vehicle" (6+ seats) definition. New York City's local commuter-benefits law carves out an exception for pooled rides in larger vehicles, but that's a city rule, not a federal one. So on your credit card statement, rideshare usually reads as transit; on your employer's pre-tax commuter account, it usually doesn't.
💡 Pro tip — If your employer offers a pre-tax transit benefit, use it for your subway or bus pass first — pre-tax dollars beat any card multiplier — and reserve your transit-earning card for tolls, parking, and rideshare that the benefit doesn't cover.
Key takeaway: cards bundle rideshare into "transit" for multiplier purposes; the federal commuter-benefit program does not — know which system you're in before assuming a purchase qualifies for either.
Which cards actually pay elevated rates on transit
| Card | Annual fee | Transit multiplier | Effective return* |
|---|---|---|---|
| Amex Green | $150 | 3x, uncapped | 3% |
| Autograph Journey | $95 | 3x ground transportation | 3% |
| Ink Preferred (business) | $95 | 3x, capped at $150k combined/year | 3% |
| Sapphire Preferred | $95 | 2x, broad travel category | 2% |
| Venture X | $395 | 2x flat (not elevated for transit specifically) | 2% |
| Sapphire Reserve | $795 | 1x, plus $300 credit auto-applies | 1% + credit |
| Strata Premier | $95 | 1x — transit is not a bonus category | 1% |
| Amex Gold | $325 | 1x — transit is not a bonus category | 1% |
*Effective return assumes 1¢ per point/mile — a conservative, cash-equivalent baseline. Transferring points to airline or hotel partners often nets more, but 1¢ is what you can count on without extra work.
Strata Premier and Amex Gold both market themselves as travel cards but earn only the base rate on tolls, parking, and rideshare — their bonus categories are air travel, hotels, dining, and groceries, not ground transportation. Don't assume "travel card" means "transit card."
Key takeaway: only Amex Green, Autograph Journey, and Ink Preferred pay 3x on transit; Sapphire Preferred is the only broad-travel card that still covers it at 2x.
Transit credits vs. rideshare credits on premium cards
Sapphire Reserve's $300 annual travel credit auto-applies to the first $300 of travel-coded spend each cardmember year — and transit (tolls, parking, subway, rideshare) is part of that broad travel category, so it clears automatically with zero booking required. A commuter spending $8-13/day on tolls and parking burns through it in 6-10 weeks, per Chase's own MCC list. The catch is the ongoing rate: once the $300 is used, transit purchases earn just 1x — the card's 2025 refresh moved the elevated 8x/4x rates to Chase Travel portal bookings and direct flights/hotels only.
Venture X's $300 credit works differently: it only reimburses purchases made inside the Capital One Travel portal — flights, hotels, rental cars, and activities. A toll charge, a subway fare, or an Uber ride paid directly never touches that credit, because none of those merchants exist inside the portal. Venture X earns a flat 2x on everything, transit included, but neither the multiplier nor the credit specifically rewards commuting.
⚠️ Biggest mistake — Assuming a card's "$300 travel credit" behaves the same way across issuers. Chase's version reimburses real-world transit spend automatically; Capital One's version only reimburses its own portal.
Key takeaway: Sapphire Reserve's credit helps a commuter directly; Venture X's credit does not, despite both being marketed as $300 travel credits.
The Amtrak case
Amtrak fares code as "passenger railways," inside the same transit/travel MCC group as buses and subways — so Amex Green and Autograph Journey both earn their 3x on train tickets, Sapphire Preferred earns 2x, and Sapphire Reserve earns 1x (with the $300 credit applying the same as any other travel purchase).
None of the major transferable-currency programs (Chase Ultimate Rewards, Amex Membership Rewards, Citi ThankYou) transfer directly to Amtrak Guest Rewards — Amtrak isn't a transfer partner of any of them. The one real path to outsized Amtrak value is Bilt Rewards, which transfers to Amtrak Guest Rewards at 1:1, and Amtrak's own points can run 2.5-3¢ each on Acela and sleeper-car routes when redeemed well. If Amtrak is a meaningful part of your commute or travel, earning Bilt points (via rent payments, dining, or its Lyft-linked rideshare bonus) and transferring them is a stronger play than chasing a transit multiplier on a card that doesn't reach Amtrak at all.
Key takeaway: Amtrak earns transit-level multipliers on the cards above like any other train purchase, but the only real transfer bridge into Amtrak's own program runs through Bilt, not Chase, Amex, or Citi.
Monthly-spend threshold framework
The question that actually matters: how much transit spend justifies each card's annual fee, on transit alone — against a no-annual-fee 1.5% flat-rate card as the baseline everyone already has access to.
Breakeven formula: monthly spend = annual fee ÷ 12 ÷ (card's transit rate − 1.5%).
| Card | Breakeven monthly transit spend |
|---|---|
| Autograph Journey (3x, $95 AF) | ~$528/month |
| Ink Preferred (3x, $95 AF, business) | ~$528/month |
| Amex Green (3x, $150 AF) | ~$833/month |
| Sapphire Preferred (2x, $95 AF) | ~$1,583/month |
| Venture X (2x, $395 AF) | ~$6,583/month — never realistic on transit alone |
| Strata Premier, Amex Gold (1x) | Never breaks even on transit spend — earns below the 1.5% baseline |
Worked example: $150/month commuter
A subway pass plus occasional rideshare runs about $150/month, $1,800/year. On Amex Green, that earns $54/year in points against a $150 fee — a $96 net loss from transit alone. On Autograph Journey, $54 against a $95 fee is a $41 net loss. A no-AF 1.5% flat card earns $27 with zero downside. At this spend level, none of the transit-bonused cards pay for themselves on commuting alone — they only make sense if dining, groceries, or other bonus categories on the same card add enough value to cover the gap.
Worked example: $400/month commuter
Bridge tolls, garage parking, and rideshare in a car-dependent metro area can easily run $400/month, $4,800/year — close to the $3,900/year heavy-commute figure Chase itself uses to describe how fast its $300 credit clears. At this level: Autograph Journey earns $144 against its $95 fee (+$49 net), Sapphire Preferred earns $96 against its $95 fee (roughly breakeven), and Amex Green earns $144 against its $150 fee (nearly breakeven, and profitable the moment you add any 3x dining spend). Sapphire Reserve's $300 credit clears in under five weeks at this rate, but the $795 fee still needs lounge access and other benefits to make sense — the transit multiplier alone doesn't carry it.
Key takeaway: transit-bonused cards need $500-$800+ a month in qualifying spend before the multiplier alone covers the annual fee — below that, a no-fee flat-rate card wins on transit, and the bonus card has to earn its keep elsewhere.
Decision framework
| Your situation | Best fit |
|---|---|
| $150-300/month transit, no other premium-card spend | No-AF flat-rate card — none of the transit cards break even yet |
| $400-800/month transit, low AF preferred | Autograph Journey or Sapphire Preferred |
| $800+/month transit, also dine out frequently | Amex Green — 3x transit plus 3x dining stacks past its fee |
| Mostly fly/stay in hotels, transit is incidental | Sapphire Reserve — credit and lounges matter more than the 1x rate |
| Regular Amtrak rider | Build Bilt Rewards and transfer 1:1 — no other program reaches Amtrak directly |
| Self-employed or gig commuter with a business card | Ink Preferred — same 3x broad-travel rate as Sapphire Preferred, business-eligible |
Key takeaway: match the card to your monthly transit total and what else you spend on, not to whichever card markets itself as a "travel" card hardest.
For the NYC-specific version of this math — real toll, subway, and rideshare numbers from an actual trip — see the New York on points trip breakdown and best NYC hotels on points. For the exact mechanics behind Sapphire Reserve's $300 credit and its 2025 earning-rate refresh, see what counts as travel for Chase's $300 credit.
Bottom line: transit is a real bonus category on exactly three cards worth caring about, and a marketing footnote on two "travel" cards that don't actually pay for it. Match the card to your monthly transit spend using the breakeven math above, not to which card has the flashiest "travel" branding — and if Amtrak matters to you, build Bilt points, because none of the major bank currencies transfer there directly.
Get weekly card offer alerts
Sunday digest of elevated bonuses. One email, zero spam.
Cards mentioned in this guide
Frequently asked questions
Does Uber or Lyft earn transit-level rewards on my card?
Are pre-tax commuter benefits better than a card's transit rewards?
Does the Chase Sapphire Reserve still earn 3x on transit?
Which card is best for Amtrak specifically?
Do premium travel cards like Amex Gold or Citi Strata Premier reward tolls and parking?
How much do I need to spend on transit monthly to justify Amex Green's $150 fee?
Related guides
Rules & Mechanics
What Counts as "Travel" for Chase's $300 Credit and 3x Categories
10 min
Strategy
Chase Sapphire Preferred vs Chase Sapphire Reserve (2026): Which Is Right for You?
10 min
Strategy
Should You Downgrade the Chase Sapphire Reserve at $795? A No-BS Guide
8 min
Rewards Programs
Best Hotels in NYC on Points: What Actually Costs Less Than Cash
9 min
Related news
bilt · Jun 2, 2026
Bilt Palladium vs CSR vs Amex Platinum 2026 ($495/$795/$895)
airlines · Jun 2, 2026
Credit Card Transfer Bonuses Mid-2026: H1 Drought Recap
industry · Jun 2, 2026
Biggest Credit Card Changes 2026: Mid-Year Retrospective

chase · Jun 10, 2026
Chase Hyatt Transfer Ratio 4:3: What It Means for Sapphire Preferred and Ink Business Preferred
Cards in this ecosystem
Considering switching?