Do Premium Cards Make Sense If You Only Travel Twice a Year? (Venture X, Reserve, Platinum)
At two trips a year, the Capital One Venture X still pays for itself because its $300 travel credit and 10,000 anniversary miles cover the $395 fee; the Chase Sapphire Reserve breaks even only if you use the Edit hotel, dining, and DoorDash credits on top of the $300 travel credit; and the Amex Platinum does not — an occasional traveler recoups about $230 of $895 in credits plus four lounge visits. Hold any of them for the welcome-bonus year, then downgrade to a Sapphire Preferred or Amex Gold plus a 2% card unless the credits fit your month regardless of travel.
On this page▾
Topic Collection
Part of the Keep or Cancel Collection
Explore all 35 articles
Two trips a year is the most common travel pattern in the country and the one premium cards are least designed for. Four lounge visits, two hotel stays, one or two checked bags — that is the whole year's worth of "travel perks," and against it stand fees of $395 to $895. The answer is not the same for all three big premium cards: one of them still makes sense at two trips a year, one makes sense only if you use its credits with discipline, and one does not, except in the welcome-bonus year.
Quick answer
At two trips a year, the Venture X still pays for itself, because its $300 travel credit and 10,000 anniversary miles cover the $395 fee before you take a single flight. The Sapphire Reserve breaks even only if you use the $300 travel credit, at least one half of the $500 Edit hotel credit, and the DoorDash and dining credits — about $700-$900 of $795 — which most two-trip travelers do not. The Amex Platinum does not: an occasional traveler recoups about $230 of $895 in credits and gets four lounge visits, leaving a $500-plus gap that no earn rate closes. The better wallet for two trips a year is a Sapphire Preferred or Amex Gold at $95-$325 plus a no-fee 2% card — unless you are in the welcome-bonus year of a premium card, when the math flips for twelve months.
- Keep at two trips a year: Venture X
- Keep only with credit discipline: Sapphire Reserve
- Downgrade or cancel after year one: Amex Platinum
- The occasional traveler's wallet: Sapphire Preferred or Amex Gold, plus a 2% card
💡 Pro tip — Count your lounge visits before you count anything else. Two round trips are four visits, and four visits at the $30 you would actually pay for a day pass is $120 — the number every premium card's lounge pitch has to be measured against.
What two trips a year actually uses
| Perk | What a two-trip year uses | Realistic value |
|---|---|---|
| Lounge access | 4 visits (2 round trips, no connections) | $120 at $30 per visit |
| Hotel credits | 2 stays, maybe 1 at a qualifying luxury property | $0-$300 |
| Airline fee credit | 1-2 checked bags, a seat selection | $100-$200 |
| Travel insurance | 2 trips' worth of delay and baggage coverage | $50-$100 if you would otherwise buy it |
| Global Entry | Renewed every 4 years | $30 a year |
| Monthly credits (Uber, DoorDash, Resy, Lyft) | Unrelated to travel; depends on your city and habits | $0-$400 |
| Portal or 5x flight earn | About $4,500 of travel spending | $70-$340 over a 2% card |
Add the travel-related rows and a two-trip year is worth about $370-$950 in premium-card benefits, depending almost entirely on whether one hotel stay happens to qualify for a credit. Below that, the monthly lifestyle credits decide the outcome — and those have nothing to do with how often you travel.
Key takeaway: for an occasional traveler the premium card is not a travel decision at all; it is a decision about whether you use Uber, DoorDash, and Resy enough to pay for a coupon book.
The three premium cards at two trips a year
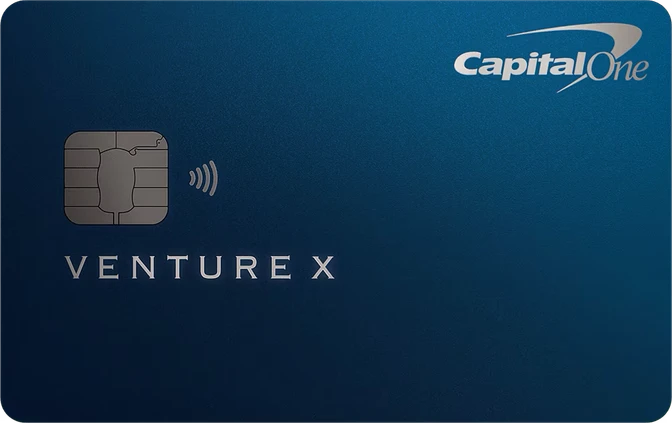
Venture X — $395: keep
The $300 Capital One Travel credit covers one of your two trips' flights or hotel. The 10,000 anniversary miles are worth about $100 at transfer partners. That is $400 against $395 before the four lounge visits, Global Entry, and 2x on everything. The Venture X survives the two-trip test because its credits are travel credits, spent on the travel you were already taking. The only trap is booking through the portal for the credit when the same flight is cheaper direct; the Venture X benefits guide explains when the portal price is fine.
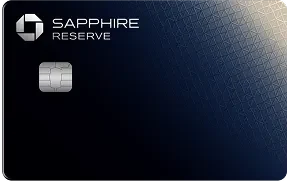
Sapphire Reserve — $795: keep only with discipline
The $300 travel credit is easy — any airfare or hotel triggers it. The rest is where two-trip travelers fall short:
| Credit | Two-trip usage | Value |
|---|---|---|
| $300 travel credit | Used on trip one | $300 |
| $500 Edit hotel credit ($250 per half) | Used only if one stay is at an Edit property in each half | $0-$500 |
| $300 dining credit ($150 per half) | Partner restaurants; unrelated to travel | $0-$300 |
| $300 DoorDash ($25 per month) | Unrelated to travel | $0-$300 |
| $120 Lyft | Unrelated to travel | $0-$120 |
| Apple TV+ and Music | Only if you subscribe | $0-$250 |
A two-trip traveler who books one Edit stay a year and uses DoorDash monthly recoups about $700-$900 and comes out roughly even before the 4x on direct travel, the Sapphire Lounge visits, and the best trip insurance of the three. One who stays at Hyatts on points and does not order delivery recoups $300-$450 and pays $350-$500 for four lounge visits. The Reserve is a keep for the first profile and a downgrade to the Sapphire Preferred for the second; should you keep or cancel the Sapphire Reserve has the full decision.
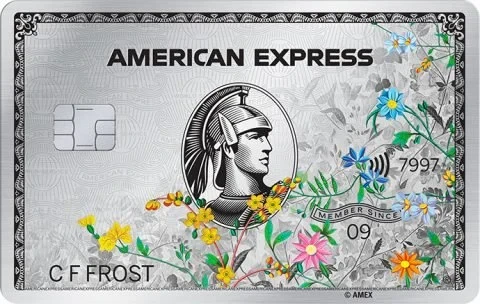
Amex Platinum — $895: downgrade or cancel after year one
The Platinum's credits are the least travel-shaped of the three. The $600 hotel credit requires prepaid Fine Hotels + Resorts or Hotel Collection bookings, which a two-trip traveler may never make; the $200 airline credit covers bags and seats; everything else — Resy, digital entertainment, Uber, Walmart+, Saks, Lululemon, Equinox, Oura — is a lifestyle coupon.
| Two-trip profile | Credits recouped | Lounge value | Net cost of the card |
|---|---|---|---|
| Uses airline credit and Global Entry only | $230 | $120 | about $545 |
| Adds one FHR stay ($300 of the hotel credit) | $530 | $120 | about $245 |
| Adds Resy, Uber, and streaming monthly | $1,130 | $120 | negative — but those are lifestyle credits, not travel |
The first two rows are the typical occasional traveler, and both leave a gap of $245-$545 that 5x on $3,000 of flights ($225 at 1.5 cents, $165 over a 2% card) does not close. The card only pays off in the third row, where it is a lifestyle subscription that happens to include lounges. After the welcome-bonus year, keep or cancel the Amex Platinum walks through the downgrade to the Amex Gold or Green.
The welcome-bonus exception
Every one of these cards is worth holding for twelve months if you are earning its welcome bonus: the bonus alone is worth more than the fee, usually by a wide margin, and the two trips you were taking anyway meet the minimum spend. The two-trip test is a year-two test. Open the premium card for the bonus, take your two trips, use whichever credits fit naturally, and decide at the second fee — which every issuer gives you a window to reverse, per annual fee refund rules by issuer.
The better wallet for two trips a year
| Wallet | Annual fees | What it does with two trips | What it costs you versus premium |
|---|---|---|---|
| Sapphire Preferred + 2% card | $95 | 3x dining, 2x travel, primary rental coverage, trip delay and baggage insurance, $50 hotel credit; transfers to Hyatt | No lounges; no $300 travel credit |
| Amex Gold + 2% card | $325 | 4x dining and groceries, 3x flights, $240 of usable credits; transfers to Amex airline partners | No lounges; weaker insurance |
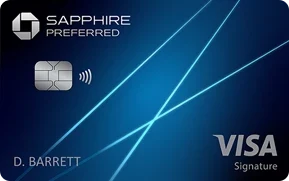
| Venture X alone | $395 | 2x everything, $300 credit, 10,000 miles, lounges, Global Entry | Nothing — this is the one premium card that fits |
For most two-trip households, the Preferred or the Gold plus a 2% card earns more on everyday spending than a Platinum does, at a fifth of the fee, and the annual fee break-even math shows the mid-tier cards paying for themselves on a few thousand dollars of category spending. The lounges are the only thing you give up, and four visits a year cost less than the difference in fees.
Real use case: a couple with two trips and $30,000 of spending
A couple takes a spring trip and a fall trip, spends $4,500 on travel, $8,000 on dining and groceries, and $17,500 on everything else.
Wallet A — Amex Platinum. Credits recouped: airline $200, one FHR night $300, Global Entry $30 — $530. Lounges: four visits, $120. Earn: $3,000 of flights at 5x ($225) plus $27,000 at 1x ($405), total $630 versus $600 on a 2% card. Net: $530 + $120 + $30 − $895 = −$215 a year.
Wallet B — Sapphire Preferred + 2% card. Credit: $50 hotel. Earn: $4,000 of dining at 3x ($180) plus $4,500 of travel at 2x ($135) plus $21,500 at 2% ($430), total $745 versus $600 baseline. Net: $50 + $145 − $95 = +$100 a year, with trip insurance included.
Wallet C — Venture X alone. Credits: $300 + $100 in miles + $30 Global Entry. Lounges: $120. Earn: $30,000 at 2x ($900) versus $600 baseline. Net: $430 + $120 + $300 − $395 = +$455 a year.
The Venture X wins, the Preferred is a solid second, and the Platinum loses by $215 — a $670 swing between the two premium cards for the same couple.
Decision framework
| You travel twice a year and... | Do this |
|---|---|
| Want lounges and one simple credit | Venture X |
| Stay at Edit-list hotels and use DoorDash monthly | Sapphire Reserve; otherwise the Preferred |
| Use Resy, Uber, and streaming credits every month regardless of travel | Amex Platinum as a lifestyle card; count the credits honestly |
| Want the most rewards on everyday spending | Amex Gold or Sapphire Preferred plus a 2% card |
| Are in a premium card's welcome-bonus year | Keep it for twelve months, then run this test at the second fee |
Common mistakes
- Valuing lounges at the day-pass price. Four visits at $50 sounds like $200; at the $30 most people would actually pay it is $120.
- Counting hotel credits you cannot use. The Platinum's $600 needs FHR or Hotel Collection prepaid bookings; the Reserve's $500 needs Edit properties. A points stay at a Hyatt triggers neither.
- Judging the card in the welcome-bonus year. Year one is always positive; year two is the test.
- Cancelling instead of downgrading. The Platinum downgrades to the Gold or Green, the Reserve to the Preferred, keeping the account age and the points.
- Ignoring the monthly-credit tax on your time. Twelve DoorDash reminders for $300 of value is work; an occasional traveler often stops doing it by March.
- Assuming "premium" means "better." At two trips a year, a $95 card with insurance and 3x dining earns more than an $895 card with lounges you visit four times.
Editor's take
Premium cards are built for people who are in an airport every month, and most of their marketing is aimed at people who are not. Our reading for the two-trip traveler: the Venture X is the exception that proves the rule, because its credits are spent on the trips you already take; the Reserve is a fair deal for the subset who use its lifestyle credits and a poor one for everyone else; and the Platinum is a welcome-bonus card to hold for a year and then downgrade, unless Resy and Uber are already part of your month. The lounges are real, but four visits a year are not worth $500, and no earn rate on two trips of spending changes that.
Related reading
- Premium card credits compared — every credit on the seven premium cards at face value and realistic value
- Annual fee break-even math — the formula behind the net-cost rows above
- Annual fee refund rules by issuer — the window to downgrade after the second fee posts
- Venture X vs Sapphire Reserve vs Amex Platinum — the three-way comparison for frequent travelers
- Should you keep or cancel the Amex Platinum? — the downgrade path
- Chase Sapphire Preferred review — the occasional traveler's default
Get weekly card offer alerts
Sunday digest of elevated bonuses. One email, zero spam.
Cards mentioned in this guide
Frequently asked questions
Is the Amex Platinum worth it if I only fly twice a year?
Which premium card is best for someone who travels only occasionally?
How much is lounge access worth if I only take two trips a year?
Should I get a premium card for the welcome bonus and then downgrade?
What is the best card setup for someone who travels twice a year?
Related guides
Card Roundups
Premium Card Credits Compared: How Much of Each $395-$895 Fee You Really Recoup
12 min
Strategy
Annual Fee Break-Even Math: The One Formula for Any Card (With Worked Numbers)
10 min
Rules & Mechanics
Annual Fee Refund Rules by Issuer: How Long You Have to Cancel or Downgrade (2026)
10 min
Strategy
Venture X vs Chase Sapphire Reserve vs Amex Platinum: Which Premium Card Earns Its Fee in 2026?
13 min
Related news
airlines · Jun 2, 2026
Aeroplan 2026: SQC Status and June 1 Devaluation
airlines · Jun 2, 2026
Credit Card Transfer Bonuses Mid-2026: H1 Drought Recap
industry · Jun 2, 2026
Travel Rewards Devaluations 2026: Every Major Loyalty Program Change This Year
industry · Jun 2, 2026
Biggest Credit Card Changes 2026: Mid-Year Retrospective
Cards in this ecosystem
Considering switching?