Primary vs Secondary Rental Car Coverage: Which Cards Give You Primary
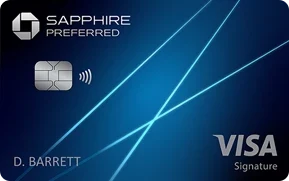
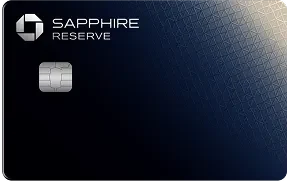
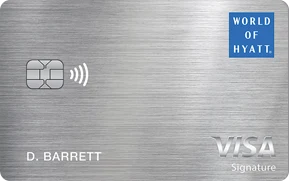
Primary rental car coverage pays the rental company directly without touching your personal auto insurer. Among catalog cards, Chase Sapphire Preferred, Chase Sapphire Reserve, World of Hyatt, and Capital One Venture X carry true primary coverage on personal rentals; most no-annual-fee cashback cards and Amex Gold are secondary-only.
On this page▾
Topic Collection
Part of the Issuer Application Rules Collection
Explore all 14 articles
A rental-car fender-bender can cost more than the flight that got you there — $3,000 to $8,000 in body damage is routine, and the wrong card leaves you filing with your own auto insurer, paying a $500–$1,000 deductible, and watching your premium climb for three years. Primary coverage on the right card skips all of that. The problem: fewer cards carry true primary coverage than most people assume, and the exclusions — exotic cars, rentals over 15 or 31 days, a short list of countries — are exactly where claims get denied.
Quick answer
Primary coverage pays the rental company directly; your personal auto policy is never touched. Secondary coverage only pays what your own insurer doesn't — you file with your insurer first, eat your deductible, and the card mops up the rest. Among catalog cards, Sapphire Preferred, Sapphire Reserve, World of Hyatt, and Venture X carry true primary coverage on ordinary personal rentals. Strata Premier flips to primary only outside your country of residence. Ink Preferred is primary for business rentals and any rental abroad — but only secondary for a personal domestic rental, which is the fine print most cardholders miss.
- Primary = file directly with the card's claims administrator, personal insurance untouched, no deductible
- Secondary = your insurer pays first, the card covers only the gap (your deductible plus anything the insurer denies)
- Amex Platinum has no free primary benefit — its Premium Car Rental Protection is a paid $12.25–$24.95-per-rental add-on that becomes primary only once you enroll before the trip
- Coverage caps at 31 consecutive days on most cards, 15 days in your home country on Venture X
- Ireland, Israel, and Jamaica are hard exclusions on nearly every Visa and Mastercard benefit guide
Key takeaway: primary coverage means the card pays first and your auto insurer never finds out; secondary coverage means your insurer pays first and the card only cleans up what's left over.
Primary vs secondary, in plain terms
The distinction isn't marketing language — it changes what happens the moment you back into a concrete pillar.
With secondary coverage, a $4,500 door-and-quarter-panel repair goes through your own auto insurer first. You pay your $500–$1,000 deductible, the claim shows on your driving record for three to five years, and even one at-fault claim commonly adds $200–$600 a year to your premium — $600–$1,800 total. Only after your insurer pays does the card's secondary benefit reimburse what's left.
With primary coverage, you file the same $4,500 claim directly with the issuer's benefits administrator (Chase uses Card Benefit Services; Capital One uses a third-party claims administrator). Your personal insurer is never contacted — no deductible, no claim on your record, no premium bump. The trade-off is a coverage cap, usually $50,000–$75,000 per rental, and exclusions that void the benefit entirely for the wrong vehicle, country, or rental length.
💡 Pro tip — Primary coverage is a rental-agency benefit, not a general auto-insurance replacement. Peer-to-peer platforms (Turo) and car-share services billed hourly (Zipcar) generally don't count as a "rental agency" under most cards' definitions — read the best credit cards for road trips guide before assuming a Turo booking is covered.
Key takeaway: secondary coverage costs you a deductible ($500–$1,000) and a multi-year premium hit ($600–$1,800); primary coverage costs you nothing out of pocket if the rental, country, and rental length all fall inside the card's rules.
Which catalog cards actually give you primary coverage
Coverage type is per-card, and several widely recommended travel cards are secondary-only — a fact that surprises a lot of cardholders mid-claim.
| Card | Annual fee | Coverage on personal rentals | Rental cap | Max coverage |
|---|---|---|---|---|
| Sapphire Preferred | $95 | Primary, worldwide | 31 days | $60,000 |
| Sapphire Reserve | $795 | Primary, worldwide | 31 days | $75,000 |
| World of Hyatt | $95 | Primary, worldwide | 31 days | $60,000 |
| Venture X | $395 | Primary | 15 days (US) / 31 days (abroad) | $75,000 |
| Strata Premier | $95 | Secondary domestically, primary outside your country of residence | 31 days | Actual cash value |
| Ink Preferred | $95 | Primary for business rentals or any rental outside the US; secondary for a personal US rental | 31 days | $60,000 |
| Amex Platinum | $895 | No free primary — paid Premium Car Rental Protection ($12.25–$24.95/rental) becomes primary once enrolled | 42 days | Varies by state |
| Amex Gold | $325 | Secondary only | — | $75,000 |
| Delta Gold | $150 | Secondary only | — | $75,000 |
| Freedom Unlimited | $0 | Secondary only | — | — |
| Venture | $95 | Secondary only | — | — |
If your only travel card is a no-AF cashback card or Amex Gold, you're carrying secondary coverage without knowing it. See the Chase Sapphire Preferred review, the Chase Sapphire Reserve review, the Capital One Venture X benefits guide, or the Citi Strata Premier review before choosing which to add for a specific trip.
Key takeaway: Sapphire Preferred, Sapphire Reserve, World of Hyatt, and Venture X are primary on ordinary personal rentals; Strata Premier and Ink Preferred are conditionally primary; nearly every no-AF cashback card and Amex Gold/Amex Platinum without enrollment are secondary-only.
The exclusions that catch people
Primary coverage isn't unconditional. Four categories of exclusion account for most of the denied claims CreditPoints hears about:
Vehicle class. Chase's own benefit guide names Ferrari, Lamborghini, Porsche, Jaguar, and Corvette rentals as excluded — "exotic" and high-value classes void the benefit on every issuer's guide, not just Chase's. Full-size cargo vans, heavier pickups, and off-road vehicles are frequently excluded too.
Rental length. Sapphire Preferred and Sapphire Reserve void coverage entirely — not just the excess days — past 31 consecutive days. Venture X caps at 15 days at home, extending to 31 only abroad. A 32-day rental isn't "covered for 31 and exposed for one" — it's uncovered from day one.
Excluded countries. Ireland (Republic and Northern), Israel, and Jamaica are named exclusions on Visa's and most issuers' benefit-guide PDFs. Rent in any of these three and the card's benefit simply doesn't apply — local counter CDW or a standalone policy is the only coverage available.
Mandatory local insurance. Australia and New Zealand require a minimum collision coverage by law. Your card's benefit becomes supplemental to that mandatory coverage rather than a full substitute — you'll still pay for some local protection at the counter.
⚠️ Biggest mistake — Assuming primary coverage travels with you everywhere the card does. Renting in Israel, Ireland, or Jamaica on Sapphire Reserve and skipping the counter's own damage waiver leaves you with zero coverage, not "secondary" coverage — full personal-insurance exposure on a car you may never have taken home.
Key takeaway: exotic/luxury vehicle classes, rentals over 15–31 days, and rentals in Ireland, Israel, or Jamaica void card coverage outright; Australia and New Zealand require you to carry mandatory local coverage alongside the card benefit.
What "decline the counter CDW" actually requires
The mechanic sounds simple and trips people up anyway:
- Decline the rental agency's own CDW/LDW at the counter — don't sign for it "just in case." Accepting the counter's waiver makes the rental company's coverage primary instead, and stacking it with your card benefit is redundant spend, not extra protection.
- Pay for the entire rental with the eligible card, the full balance start to finish — a deposit on one card and the remainder in cash or on another card is the single most common reason issuers deny a claim. This includes third-party OTA bookings (Expedia, Priceline): pay the deposit and the counter balance on the same card.
- Be listed on the rental agreement as the renter, or as an authorized additional driver where the card's terms allow it. An unlisted driver in an accident generally isn't covered under any issuer's terms.
Key takeaway: decline the counter's own damage waiver, pay 100% of the rental on the eligible card, and make sure your name is on the rental agreement — miss any one of the three and the claim gets denied regardless of coverage type.
How to file a claim
Documentation determines whether a $4,000 claim gets paid in six weeks or gets denied on a technicality.
- Report the damage or theft to the rental company immediately and get a copy of the rental agreement plus its damage report. File a police report for any theft or injury — several issuers require it before opening a claim.
- Call the card's benefits administrator within the notification window (Citi: 180 days; most issuers want notice within 30–60 days even if final documents take longer). The number is on the Guide to Benefits document or the back of the card.
- Submit rental agreement, itemized repair invoice, proof you declined the counter CDW, and the police report if applicable. Expect resolution in four to eight weeks once the file is complete — incomplete submissions are the most common cause of delay.
Real use case: a renter with Venture X backs a Hertz rental into a parking-garage pillar, causing $4,200 in door and bumper damage. They declined Hertz's own CDW at the counter and paid the full $612 rental on the Venture X. Capital One's claims administrator pays the $4,200 repair invoice directly to Hertz — the renter's personal Geico policy is never contacted, no $500 deductible, no record claim, and an estimated $450–$900 avoided in higher premiums over the next three years.
Key takeaway: notify within days, submit rental agreement plus itemized damage documentation, and expect four to eight weeks for a complete file — skipping the police report on a theft claim is the most common reason a primary-coverage claim stalls.
Decision framework: is card coverage enough for this trip
If you rent domestically 2–3+ times a year and want to stop paying $15–$30/day for counter CDW, a card that's already primary (no added annual fee beyond what you'd carry anyway) saves roughly $45–$150 per rental in skipped counter charges, on top of protecting the $500–$1,000 deductible exposure a secondary-only card leaves open.
If you already spend enough to justify a $95 travel card — Sapphire Preferred pays for its $95 annual fee in avoided counter CDW after roughly 3–4 rental days a year, before counting any of its points-earning value.
If your trip involves Ireland, Israel, Jamaica, a rental over 31 days, or an exotic-class vehicle, no catalog card's primary benefit reaches it — budget $9–$14/day for a standalone product (Allianz, AIG) or accept the counter's own CDW for that leg.
If you're renting for business or renting abroad on a company trip, Ink Preferred converts to primary automatically — skip the separate purchase.
| Rental scenario | Coverage that applies | What to budget |
|---|---|---|
| Domestic rental, standard sedan, ≤31 days, on Sapphire Preferred | Primary, $60,000 cap | $0 extra — decline counter CDW |
| Domestic rental on Amex Gold or a no-AF cashback card | Secondary only | Your $500–$1,000 deductible remains exposed |
| Rental in Ireland, Israel, or Jamaica | No card coverage on any catalog card | $9–$14/day standalone policy or counter CDW |
| Exotic/luxury class (Ferrari, Porsche, Corvette) | Excluded on every issuer | Counter CDW or standalone policy |
| Business rental abroad on Ink Preferred | Primary, $60,000 cap | $0 extra |
For international travel beyond the excluded countries, primary coverage on Sapphire Reserve or Venture X generally travels with you — the country list above is short, and it's the exception, not the rule.
Key takeaway: for ordinary domestic and most international rentals, primary-coverage cards eliminate counter CDW spend entirely; for excluded countries and vehicle classes, budget a standalone daily rate instead of assuming the card has you covered.
Get weekly card offer alerts
Sunday digest of elevated bonuses. One email, zero spam.
Cards mentioned in this guide
Frequently asked questions
What is the difference between primary and secondary rental car insurance?
Which credit cards give primary rental car coverage on personal rentals?
Does credit card rental car insurance work in Ireland or Israel?
How many days can I rent a car and still be covered by my credit card?
Do I have to decline the rental company's own insurance to get credit card coverage?
How long do I have to file a rental car insurance claim with my credit card?
Related guides
Strategy
Chase Sapphire Preferred Review 2026: Refreshed Benefits, New Hyatt Ratio, Still Worth $95?
12 min
Card Roundups
Chase Sapphire Reserve Review 2026: Worth the $795 Annual Fee?
12 min
Strategy
Capital One Venture X: Every Benefit Explained (2026)
12 min
Card Roundups
Citi Strata Premier Review 2026: Best $95 Travel Card You're Overlooking
12 min
Related news
chase · Jun 10, 2026
Chase Hyatt Transfer Ratio 4:3: What It Means for Sapphire Preferred and Ink Business Preferred
hyatt · Jun 3, 2026
Hyatt Added Perk for Globalists, Explorists and Cardholders
hyatt · Jun 2, 2026
Hyatt’s Chart Change Just Repriced Your Chase Points
chase · Jun 2, 2026
Chase Ultimate Rewards 2026: Cash-Back + Points Boost
Cards in this ecosystem
Considering switching?