Your First Year with Amex: A 12-Month Beginner Roadmap
Open the Amex Gold first unless you already spend $2,000 or more a year on what the Platinum reimburses. Check the pop-up before applying, meet the welcome offer on ordinary spending, enroll every credit in week one, wait 90 days before a second Amex, make the first transfer to a fixed-chart partner for a confirmed award, and call for a retention offer in month 11. An October opening collects the Platinum's calendar-year credits twice inside one fee.
On this page▾
Topic Collection
Part of the Keep or Cancel Collection
Explore all 35 articles
The first year with American Express is decided by two rules most people learn too late: a welcome offer is once per lifetime per card, and Amex tells you before you apply whether you are eligible for it. Get those two right, pick the card whose credits you will actually use, and a first Amex year returns several hundred dollars of credits plus a welcome offer worth $1,500 or more in travel. Get them wrong, and you spend $325 or $895 on a card that pays you nothing extra.
This is the month-by-month plan: which card to open and why, what to do in the first 90 days, when the second card fits, how to make the first transfer, and what to say on the phone before the second annual fee posts.
Quick answer
Open the Amex Gold first unless you already spend more than $2,000 a year on the things the Amex Platinum reimburses. Check the pop-up before applying, meet the welcome offer on spending you already do, enroll every monthly credit in week one, and add a second Amex only after 90 days. Make your first transfer in the second half of the year to a fixed-chart partner for a specific award, and call for a retention offer in month 11 before you decide whether to keep, downgrade, or cancel.
- First card for most people: Gold — 4x at restaurants and U.S. supermarkets, $240 a year of dining and Uber credits, $325 fee
- First card for frequent flyers who use credits: Platinum — $895 fee, lounges, and a credit stack that only pays if you spend on it anyway
- First card for a side business: Blue Business Plus — 2x on everything up to $50,000, no fee, no personal-credit reporting
- The two rules: once per lifetime per card, and no more than 2 new Amex credit cards in 90 days
- The Q4 bonus nobody mentions: calendar-year credits reset on January 1, so a card opened in October collects them twice inside one annual fee
💡 Pro tip — Amex publishes the welcome offer's own eligibility check: the "pop-up" that appears during the application before any hard pull. If it says you are not eligible, close the window; applying anyway gets you the card, the fee, and no bonus. The Amex application rules guide walks through every rule this roadmap relies on.
Before you apply: the rules that shape the year
| Rule | What it means for a first-year plan |
|---|---|
| Once per lifetime | You get each card's welcome offer once, ever. Do not open the Gold on a small offer if a bigger one appears a few times a year; the once-per-lifetime guide covers when to wait |
| The pop-up | Amex's eligibility check runs before the hard pull. A pop-up means no bonus on that application. Never proceed through one |
| 2 in 90 | No more than two new Amex credit cards in any 90 days; a 5-day gap between applications is safest |
| Card limits | Roughly 4-5 Amex credit cards and about 10 charge cards. Gold, Platinum, and Green are Pay Over Time charge cards, so they do not use the credit-card slots |
| Chase 5/24 | Amex does not count your other cards, but Chase counts Amex ones. If Chase is in your plans, open Chase first; see the Chase 5/24 guide |
| Referrals | Since April 8, 2026, each of your Amex cards can pay a referral bonus at most 5 times a calendar year — a household with two people can still refer each other |
Month 0: pick the first card
The right first card is the one whose credits you would spend on anyway. Points are a bonus; credits are the fee coming back.
| Card | Annual fee | Earns | Credits worth counting | Open it first if... |
|---|---|---|---|---|
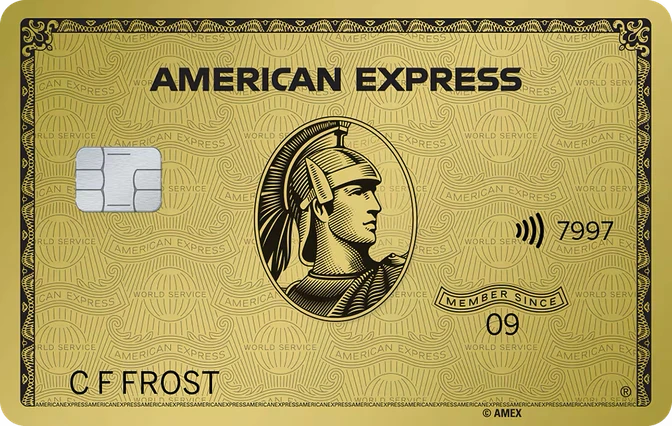
| Amex Gold | $325 | 4x restaurants worldwide, 4x U.S. supermarkets (up to $25,000 a year), 3x flights, 1x other | $120 dining credit ($10 a month at Grubhub, Cheesecake Factory and partners) + $120 Uber Cash ($10 a month) = $240; $100 credit on 2-night Hotel Collection stays | You eat out and buy groceries — most people |
| Amex Platinum | $895 | 5x flights booked direct or through Amex Travel (up to $500,000 a year), 5x prepaid hotels through Amex Travel, 1x other | $600 hotel credit (two $300 halves, prepaid Fine Hotels + Resorts or Hotel Collection), $200 airline fee, $400 Resy ($100 a quarter), $300 digital entertainment, $200 Uber Cash, $120 Uber One, $155 Walmart+, $100 Saks, $300 Lululemon, $219 CLEAR, $120 Global Entry — plus Centurion and Priority Pass lounges | You fly 6+ times a year and already spend on 3-4 of those credits |
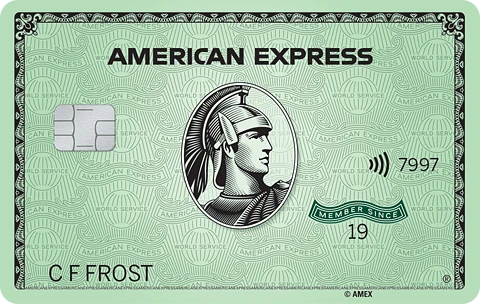
| Amex Green | $150 | 3x travel, transit, and restaurants; 1x other | Fewer credits; the cheapest way into transferable points for commuters | You want 3x on transit and travel at a low fee |
| Blue Business Plus | $0 | 2x on everything up to $50,000 a year, then 1x | None; the fee is $0 | You have any self-employment income and want a no-fee 2x earner |
| Amex EveryDay | $0 | 2x U.S. supermarkets (up to $6,000 a year), 20% points bonus with 20+ transactions in a billing period | None | You want Membership Rewards with no fee and mostly buy groceries |
The Gold wins for most first-year cardholders because its $240 of monthly credits are spent on ordinary life and its 4x categories are where most households spend most. The Platinum only wins when its credits are already your spending; our Amex Gold vs Amex Platinum comparison and how to maximize Amex Platinum credits show the arithmetic. The welcome offer on the Gold is currently 100,000 points after $8,000 in 6 months; the Platinum's is 175,000 points after $12,000 in 6 months, and Platinum offers are frequently personalized, so check the pop-up tool for yours.
Key takeaway: choose the first Amex by credits you already spend on, not by the size of the welcome offer. A $895 card whose credits you use pays for itself; a $325 card whose credits you forget does not.
Months 1-3: the welcome offer, the credits, and the setup
Week 1:
- Enroll every credit. Amex credits are not automatic. The Gold's dining credit and Uber Cash, and the Platinum's Resy, digital entertainment, Uber, Walmart+, and airline credits all require one-time enrollment in the app. A credit you did not enroll is a credit you did not get.
- Set the airline for the Platinum's $200 fee credit — it can only be changed once a year in January.
- Turn on autopay for the full statement balance. Charge cards expect payment in full; Pay Over Time is optional and expensive.
- Add Amex Offers to the card as they appear; the Amex Offers strategy guide covers how the targeted merchant offers work.
Weeks 1-12: 5. Meet the welcome offer on spending you already do — groceries, dining, insurance, the phone bill. Do not buy things to hit the number; the minimum spend strategy guide covers the honest ways to front-load real expenses. The bonus posts 8-12 weeks after you cross the threshold. 6. Add an authorized user if a partner will need transfers. Amex only transfers points to a loyalty account in your name or an authorized user's after 90 days on the card, so the clock starts now. Gold authorized users are free; Platinum ones are $195 each and get their own lounge access.
The October advantage: calendar-year credits reset on January 1
Several Platinum credits run by calendar year or half-year, not by cardmember year. A card opened in October collects the October-December allotment, then a full new allotment on January 1 — all inside the first annual fee:
| Platinum credit | Cadence | Opened in October, first cardmember year gets |
|---|---|---|
| $200 airline fee credit | Calendar year | $200 in 2026 + $200 in 2027 = $400 |
| $600 hotel credit | $300 per half-year | $300 (Jul-Dec 2026) + $300 (Jan-Jun 2027) + $300 (Jul-Sep 2027) = $900 |
| $100 Saks credit | $50 per half-year | $50 + $50 + $50 = $150 |
| $400 Resy credit | $100 per quarter | Q4 2026 + Q1-Q3 2027 = $400 |
| $300 Lululemon credit | $75 per quarter | Q4 2026 + Q1-Q3 2027 = $300 |
The Gold's credits are monthly, so timing does not change them. But for anyone leaning Platinum, an October application is the single most valuable timing decision of the first year — it can put $1,000 or more of extra credits inside the first fee, provided you would spend on those categories anyway.
Months 3-6: the second card, or no second card
By month four the welcome offer has posted and the 90-day authorized-user clock has run. Three paths:
- Gold first, then Platinum. The classic pairing: Gold for dining and groceries, Platinum for flights, hotels, and lounges. Apply for the Platinum only when a trip that uses the hotel and airline credits is on the calendar, and only if the pop-up clears. This is the core of the Amex Trifecta.
- Gold first, then Blue Business Plus. For anyone with freelance or side income, the $0 Blue Business Plus adds 2x on everything the Gold earns 1x on, does not report to personal credit, and does not count against Chase 5/24. Can I get a business credit card covers eligibility for sole proprietors.
- No second card. If the Gold is covering your spending and the first bonus was the goal, stop. A second Amex within the first year is optional; a second annual fee you do not use is a mistake.
Either way, keep the 2-in-90 rule and a five-day gap, and never apply through a pop-up. If a household member is also building an Amex setup, refer each other through the app: each referral pays the referrer a bonus, up to five per card per calendar year.
Months 6-9: the first transfer
Membership Rewards are worth 1 cent each on flights through Amex Travel with no availability required. The first transfer should beat that clearly — about 2 cents per point on a specific award you have already found.
- Pick the trip first, then the partner. Amex Membership Rewards transfer partners lists all 20 with ratios and posting times.
- Confirm the award is bookable on the partner site today. The award availability explainer is the pre-transfer checklist.
- Transfer the exact rounded amount — Amex moves points in 1,000-point blocks — and book within the hour for fast partners such as Aeroplan, Flying Blue, Virgin Atlantic, and Singapore.
- Skip Delta and JetBlue for the first transfer unless the award clears comfortably: those two carry a 0.06-cent-per-point excise fee.
A good first-year target is a one-way premium award — a Flying Blue Promo Reward to Europe, an Avios short-haul, or an Iberia off-peak business seat — rather than an aspirational round trip that needs a balance you do not have yet. Amex Membership Rewards sweet spots has the shortlist.
Months 9-12: the retention call and the keep-or-cancel decision
About 30 days before the annual fee posts, call the number on the back of the card and ask whether there are any offers on the account. Amex retention offers — a points bonus, a statement credit, or both — are common on the Gold and Platinum for cardholders who use the card, and the retention offers guide has the script. Then decide:
| If in year one you... | Do this |
|---|---|
| Used most of the Gold's $240 credits and earned 30,000+ points on 4x categories | Keep it; the card is paying for itself |
| Used under $120 of Gold credits | Product-change to the Amex Green ($150) or the Amex EveryDay ($0) to keep the account and the points; downgrade Amex Platinum to Gold or Green covers the family paths |
| Used $1,500+ of Platinum credits and flew through lounges | Keep it, especially with the calendar-year credits resetting again in January |
| Used under $900 of Platinum credits | Downgrade to Gold or Green before the fee posts; should you keep or cancel Amex Platinum has the full framework |
Never cancel with a Membership Rewards balance and no other MR card open — the points go with the account. Transfer them, redeem them, or downgrade instead.
Real use case: opening the Gold on October 10
A cardholder opens the Amex Gold on October 10, 2026, with normal monthly spending of $900 at restaurants and supermarkets and $1,400 elsewhere.
- Welcome offer: $8,000 of ordinary spending clears inside the 6 months window; the 100,000 points post in January and are worth about $1,500-$2,000 at 1.5-2 cents through a partner.
- Credits, first cardmember year: $10 dining + $10 Uber Cash for each of 12 months = $240, against a $325 fee — a net fee of $85 if every monthly credit is used.
- Points from spending: $10,800 a year at 4x is 43,200 points; $16,800 at 1x is 16,800 — about 60,000 points, worth $600-$1,200 depending on redemption.
- Month 6: an authorized user added in October is transfer-eligible; the couple transfers 50,000 points to Flying Blue for two Promo Reward seats to Paris in spring, confirmed bookable before the transfer.
- Month 11: the retention call yields a modest points offer; with $240 of credits used and about 100,000 points earned, the card stays.
First-year value: roughly $2,300-$3,400 in points and credits for a $325 fee, on spending that was going to happen anyway.
Common mistakes
- Applying through a pop-up. The card arrives, the fee posts, the bonus never does. Close the window.
- Forgetting to enroll credits. Uber Cash, the dining credit, Resy, digital entertainment, and the airline credit all need one tap in the app. Do it the day the card arrives.
- Opening the Platinum in January. It works, but an October opening collects the calendar-year and half-year credits twice inside one fee.
- Manufacturing the minimum spend. Gift cards and cash-equivalents can be excluded from the welcome offer, and Amex claws back bonuses it deems abusive. Real spending only.
- Transferring points speculatively. Transfers are one-way. Find the award, confirm it, then move the exact amount.
- Canceling with a points balance. Membership Rewards close with the last MR card. Downgrade or transfer first.
Editor's take
The first Amex year is easier than the first Chase year in one way and harder in another. Easier, because there is no 5/24 clock and the Gold is an obvious first card for almost everyone who eats. Harder, because Amex's once-per-lifetime rule means every application is a permanent decision — you do not get to redo a small welcome offer later, and you do not get a second chance at a card you applied for through a pop-up. Our advice is to slow down: one card in October, the credits enrolled the same week, the bonus earned on ordinary spending, and a second card only when a specific trip makes the Platinum's credits real. The households that do this end the year with $2,000-$3,000 of value and every future option open. The ones that open three cards in six months usually end it with a pop-up.
Related reading
- Amex application rules explained — every rule this roadmap depends on
- Amex Gold card review — the first card in detail
- Amex Platinum review — the credit stack and who it fits
- Amex Membership Rewards transfer partners — where the first transfer goes
- Amex retention offers: how to ask — the month-11 call
- Your first year with Chase — the sister roadmap, and why Chase should come first if you want both
Get weekly card offer alerts
Sunday digest of elevated bonuses. One email, zero spam.
Cards mentioned in this guide
Frequently asked questions
Which Amex card should I get first?
What is the Amex pop-up and what should I do if I see it?
Is October a good time to open the Amex Platinum?
How soon can I get a second Amex card?
Can I transfer my Amex points to my partner's airline account in the first year?
Related guides
Related news
amex · Jun 2, 2026
Amex 30% Avios Transfer Bonus: 1,000 MR = 1,300 Avios, Ends ~June 21 2026
amex · Jun 9, 2026
Amex Renames Green Card to "Classic Green" August 2026 — What Changes (Spoiler: Almost Nothing)
amex · Jun 2, 2026
Amex Gold 60th Anniversary Refresh 2026: Who Wins?
airlines · Jun 2, 2026
Aeroplan 2026: SQC Status and June 1 Devaluation
Cards in this ecosystem
Considering switching?