🏆 CreditPoints Top 5 — Best Credit Cards Right Now
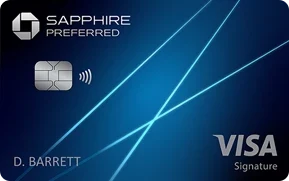
#1 right now is Chase Sapphire Preferred — 75,000 points for $5,000 spend, $95 fee. #2 is the no-annual-fee Chase Ink Business Unlimited — $1,000 cash back, worth 75,000 transferable points if paired with a Sapphire or Ink Preferred card. Rounding out the list: Chase Ink Business Preferred (#3), Amex Platinum (#4), and Capital One Venture X (#5).
On this page▾
Topic Collection
Part of the Business Credit Cards Collection
Explore all 39 articles
This is CreditPoints Top 5 — our ranking of the strongest credit card offers live right now, based on the actual welcome bonus, the annual fee, transfer partners, and travel benefits. Not a review. Not a generic "best cards" list recycled from last year. Five cards, ranked, with the real math behind each one.
Welcome offers change constantly. Check the offers page for daily updates on what's currently elevated — this page itself is reviewed and refreshed whenever the ranking changes (see the "Updated" date below).
Quick answer
#1 is Sapphire Preferred — 75,000 Ultimate Rewards points for $5,000 spend, just a $95 annual fee. #2 is the no-annual-fee Ink Unlimited — $1,000 cash back for $8,000 spend, free forever, and worth 75,000 transferable points if you pair it with a Sapphire or Ink Preferred card. Rounding out the list: Ink Preferred (#3), Amex Platinum (#4), and Venture X (#5).
🏆 #1 — Sapphire Preferred
The offer: 75,000 Ultimate Rewards points after $5,000 spend in 3 months. $95 annual fee.
Why it's #1: At just a $5,000 spend threshold and a $95 fee, this is one of the most accessible high-value offers on the market, and remains the best entry point into Chase's transferable-points ecosystem.
The math: ⚠️ Sapphire Preferred transfers to World of Hyatt at 4:3, not 1:1 — Chase devalued this specific transfer 25% starting June 15, 2026, and the transition period for existing cardholders ended October 1, 2026, so the 4:3 rate now applies to everyone (only Sapphire Reserve still gets the full 1:1). 75,000 Ultimate Rewards points become 56,250 Hyatt points, worth roughly $1,125 in hotel value at a realistic ~2¢/point redemption — net $1,030 after the $95 fee, in your first year, before you've earned a single point from spending.
Long-term value: 3x on dining, 3x on online groceries, 3x on select streaming, 25% more value when booking travel through Chase Travel, and full access to Chase's transfer partner list — World of Hyatt (now 4:3 on this card, still 1:1 on Sapphire Reserve), United, Southwest, Air France/KLM, British Airways, Virgin Atlantic, Aer Lingus, Iberia, JetBlue. Trip cancellation/interruption coverage up to $10,000, primary rental car coverage, and Purchase Protection are included at no extra cost.
Who should get it: Anyone new to the Chase ecosystem who isn't at 5/24 (5+ new cards in 24 months triggers an automatic Chase denial — check your count first). The best single entry point into transferable points.
Who should skip it: If you're at 5/24, Chase will deny you regardless of how good the offer is. If you don't travel at all, a flat-rate cashback card will out-earn this on pure math.
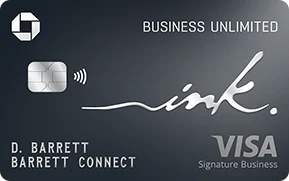
🥈 #2 — Ink Unlimited
The offer: $1,000 cash back after $8,000 spend in 4 months. $0 annual fee — forever.
Why it's #2: This is the highest bonus Chase has ever offered on its no-annual-fee Ink cards. $1,000 in pure cash back with zero ongoing cost is rare on its own. What makes it genuinely powerful is what happens if you already hold (or open) a Chase points-earning card like the Sapphire Preferred above: the cash back on this card can convert into transferable Ultimate Rewards points instead of a statement credit — turning a $1,000 cashback card into the same 75,000-point pool that's worth roughly $1,125 in travel through the Sapphire Preferred's transfer partners (at the current 4:3 Hyatt ratio — see the #1 entry above).
The math: $1,000 cash back on its own, on a card that costs nothing to hold, is a pure $1,000 profit day one. Paired with a UR-earning card, that same bonus is worth up to double as travel.
Long-term value: 1.5% cash back on every purchase, no categories to track, no caps. Also carries the same Purchase Protection and Extended Warranty as Chase's premium cards, at $10,000 per item and $50,000 per year — a $0-fee card matching benefits usually reserved for $550+ cards.
Who should get it: Any small business owner, freelancer, or sole proprietor — eligibility is broader than people assume; a simple side business qualifies. Especially strong if you already hold or plan to open a Sapphire or Ink Preferred card.
Who should skip it: Chase limits you to one welcome bonus across Ink Cash and Ink Business Unlimited combined — you can't get this bonus on both. Pick whichever's ongoing earning structure fits your spending better.
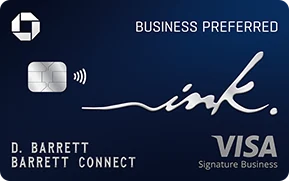
🥉 #3 — Ink Preferred
The offer: 100,000 Ultimate Rewards points after $8,000 spend in 3 months. $95 annual fee.
Why it's #3: Unlike the Ink Unlimited above, this card earns Ultimate Rewards points natively — no pairing required. It's the business-card equivalent of the Sapphire Preferred, and it's the card that makes Ink Cash/Unlimited's cash back convertible to points in the first place.
The math: Same 100,000-point math as Sapphire Preferred, and the same catch: Ink Business Preferred transfers to World of Hyatt at 4:3, not 1:1, same as above. 100,000 points become 75,000 Hyatt points — roughly $1,500 in travel value, net $1,405 after the fee.
Long-term value: 3x on travel, shipping, internet/cable/phone services, and advertising purchases (up to $150,000 combined per year, then 1x), plus the full Chase transfer partner list. Cell phone protection on business lines when you pay the bill with the card.
Who should get it: Business owners who want their Ink Cash/Unlimited cash back to become transferable points — this card is the "engine" that makes that conversion possible, plus it earns its own bonus points on business categories most side businesses already spend on.
Who should skip it: If you don't spend $8,000 in 3 months on a business, or don't have a business at all — this specific offer isn't accessible.
#4 — Amex Platinum
The offer: Up to 175,000 Membership Rewards points after $12,000 spend in 6 months. $895 annual fee.
Why it's #4: The highest single welcome bonus among personal cards on this list, and the deepest travel-benefit stack — but the $12,000 spend requirement and $895 fee put it out of reach for a lot of people, which is why it sits at #4 rather than #1 despite the bigger number.
The math: 175,000 Membership Rewards points, transferred to a sweet-spot airline partner at a realistic ~2¢/point, is worth roughly $3,500 in travel value — the single biggest bonus on this list by dollar value, before counting the card's credits.
Long-term value: Centurion Lounge access, Priority Pass, Delta Sky Club access on same-day Delta flights, up to $200 in annual airline incidental credits, $200 Uber Cash, hotel elite status (Marriott Gold, Hilton Gold) via Fine Hotels+Resorts and status match, and Extended Warranty covering manufacturer warranties up to 5 years — the widest eligibility window of any card on this list.
Who should get it: Frequent flyers who will actually use the lounge access and travel credits — the credits are real money, but only if you spend on the specific things they're tied to (Uber, specific airline incidentals, Saks).
Who should skip it: If you won't use at least $500+ of the annual credits, or don't fly enough to justify $895/year, the Sapphire Preferred or Ink Preferred above deliver similar per-point value at a fraction of the fee.
#5 — Venture X
The offer: 75,000 miles after $4,000 spend in 3 months. $395 annual fee.
Why it's #5: The smallest welcome bonus on this list in raw numbers, but the annual fee math is the best of any premium card here. A $300 annual travel credit (through Capital One Travel) plus 10,000 anniversary bonus miles (worth ~$100) effectively refunds $400 of the $395 fee — the card pays for itself before you spend a dollar on purchases.
The math: 75,000 miles at a baseline 1¢/mile (redeemable as a statement credit against any travel purchase) is worth $750. Transferred to a partner like Turkish Airlines Miles&Smiles or Virgin Atlantic for a sweet-spot redemption, the same miles can be worth $1,000-1,500.
Long-term value: Priority Pass lounge access plus Capital One's own growing lounge network, primary rental car collision coverage, and — notably — no Chase-style application restrictions, so it's the strongest alternative for anyone at 5/24 who's locked out of the Sapphire Preferred or Ink cards above.
Who should get it: Anyone who wants premium travel benefits without Chase's 5/24 restriction, or who wants the simplest "flat value" premium travel card — 2x miles on everything, no categories.
Who should skip it: If you're not at 5/24 and want the deepest single benefit stack, Amex Platinum's credits and lounge network go further at a higher fee. If you don't travel, the annual fee doesn't pay for itself no matter how you redeem the miles.
By category: more picks, verified current
The five above are the best all-around offers. These seven cover specific situations the Top 5 doesn't — each one checked against the live offer catalog, not carried forward from an old snapshot.
🏆 Best premium travel card — Sapphire Reserve 100,000 Ultimate Rewards points after $6,000 spend in 3 months. $795 annual fee. Same 1:1 Hyatt transfer as the Preferred above — the Reserve is the one Sapphire card the 4:3 devaluation didn't touch. 100K points at a realistic 2¢/point redemption is worth roughly $2,000 in hotel stays, plus a $300 annual travel credit and Priority Pass lounge access. Skip it if you're at 5/24 (Chase will deny you) or don't travel enough to use the credits — the Sapphire Preferred in the Top 5 above delivers similar per-point value for $700/year less.
🏠 Best for rent payments — Bilt Obsidian $200 Bilt Cash on account opening, $95 annual fee. The only card that earns points on rent (up to 1.25x) without a processing fee, offset by 4% on other spend. Also earns 3x on dining or groceries (pick one; groceries capped at $25K/year), 2x on travel, plus a $100 hotel credit. Points transfer 1:1 to World of Hyatt, American Airlines, United, Air France/KLM, and Cathay Pacific — the same transfer economics as Chase Ultimate Rewards, earned on a bill you're paying anyway.
💰 Best flat-rate cashback — Active Cash $100 cash bonus after $500 spend in 3 months, $0 annual fee, 2% cash back on every purchase with no categories to track and no caps. The "put it in your wallet and forget it" card — mathematically beats any 1.5% flat card and matches Citi Double Cash without the two-step redemption.
🚫 Best for 0% APR / balance transfer — WF Reflect 21 months at 0% APR on both balance transfers and new purchases — the longest 0% window of any major US card, $0 annual fee. On $5,000 of debt at 25% APR, that's roughly $1,050+ saved in year one after the transfer fee. The 0% period ends if you miss a minimum payment.
📈 Best for building credit — Discover it Secured $200 refundable deposit, $0 annual fee, 2% cash back on gas and restaurants (up to $1,000/quarter combined), 1% on everything else — and Discover automatically doubles all of it at the end of year one. Reports to all three bureaus from day one and reviews for an automatic upgrade to unsecured after about 7 months of on-time payments.
💼 Best business card — Amex Business Platinum Up to 300,000 Membership Rewards points after $20,000 spend in 3 months (personalized — offer varies by applicant). $895 annual fee. 5x on flights and prepaid hotels booked through Amex Travel, plus Centurion Lounge and Priority Pass access. The credits (Dell, Indeed, Adobe, wireless) are only worth it if you'd actually spend on those services anyway.
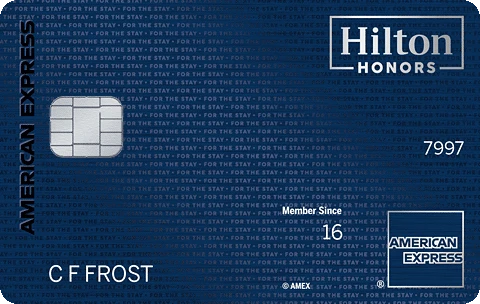
🏨 Best premium hotel card — Hilton Aspire 200,000 Hilton Honors points after $6,000 spend in 6 months (through January 13, 2027) — Hilton's best-ever offer on this card. $550 annual fee, offset by a $400 Hilton resort credit, $400 flight credit, and automatic Hilton Diamond status (top-tier breakfast, lounge access, upgrades). At a realistic ~0.6¢/point, the welcome bonus alone is worth roughly $1,200.
Not sure which one is right for you?
There's no universal "best card" on this list — the right pick depends on your current cards, your Chase 5/24 status, your spending categories, whether you have any business income, and your actual travel goals. This is exactly what our free Facebook community is for. Post your situation — current cards, 5/24 status, spending habits, travel goals — and get a real, personalized answer, not a generic recommendation. Join the CreditPoints Facebook Group.
Things to know before applying
1. Chase 5/24 blocks three of the top five. Sapphire Preferred, Ink Business Unlimited, and Ink Business Preferred are all Chase cards — if you've opened 5+ cards (any issuer) in the last 24 months, Chase will deny you automatically regardless of how strong the offer is. Check your count first.
2. You can only get one Ink Cash/Ink Business Unlimited bonus. Chase treats these as the same bonus pool — pick one, not both.
3. Run the math for your own spending before applying for anything over $250 in annual fee. A great welcome bonus doesn't automatically mean the ongoing card is right for you long-term.
Updated regularly
This ranking is re-verified whenever offers meaningfully change — not on a fixed monthly schedule. Bookmark this page, or check the offers page for daily updates on what's currently elevated.
Affiliate disclosure: CreditPoints earns referral commissions when readers apply through our links. This doesn't change which cards we rank — we only feature offers we've verified are genuinely live and worth considering.
Related content
- The sibling benefits: Best credit cards for Purchase Protection · Best credit cards for Extended Warranty
- Chase business cards: Chase Ink Business Cards guide
Get weekly card offer alerts
Sunday digest of elevated bonuses. One email, zero spam.
Cards mentioned in this guide
Frequently asked questions
Why is Chase Ink Business Unlimited's bonus described as "100,000 points" when it's a cash back card?
I'm at Chase 5/24 — which of these five can I still get?
How do I know which of these five is actually right for me?
Do Sapphire Preferred and Ink Business Preferred still transfer to World of Hyatt at 1:1?
Related guides
Card Roundups
Best Credit Cards for Purchase Protection in 2026
8 min
Card Roundups
Best Credit Cards for Extended Warranty in 2026
8 min
Strategy
Chase Ink Business Cards Guide (2026): Which Ink Card to Get + the 5/24 Workaround
17 min
Rules & Mechanics
Primary vs Secondary Rental Car Coverage: Which Cards Give You Primary
9 min
Related news
industry · Jun 2, 2026
Biggest Credit Card Changes 2026: Mid-Year Retrospective
bilt · Jun 2, 2026
Bilt Palladium vs CSR vs Amex Platinum 2026 ($495/$795/$895)
industry · Jun 2, 2026
Travel Rewards Devaluations 2026: Every Major Loyalty Program Change This Year
amex · Jun 2, 2026
Amex Platinum at $895: One Year Post-Refresh Verdict
Cards in this ecosystem
Considering switching?